01 / The model portfolio
Find the tool for your question.
Each model has its own repository, methodology, tests and development path. Start with its scope and evidence before using its results.
Counterparty credit riskProject snapshot
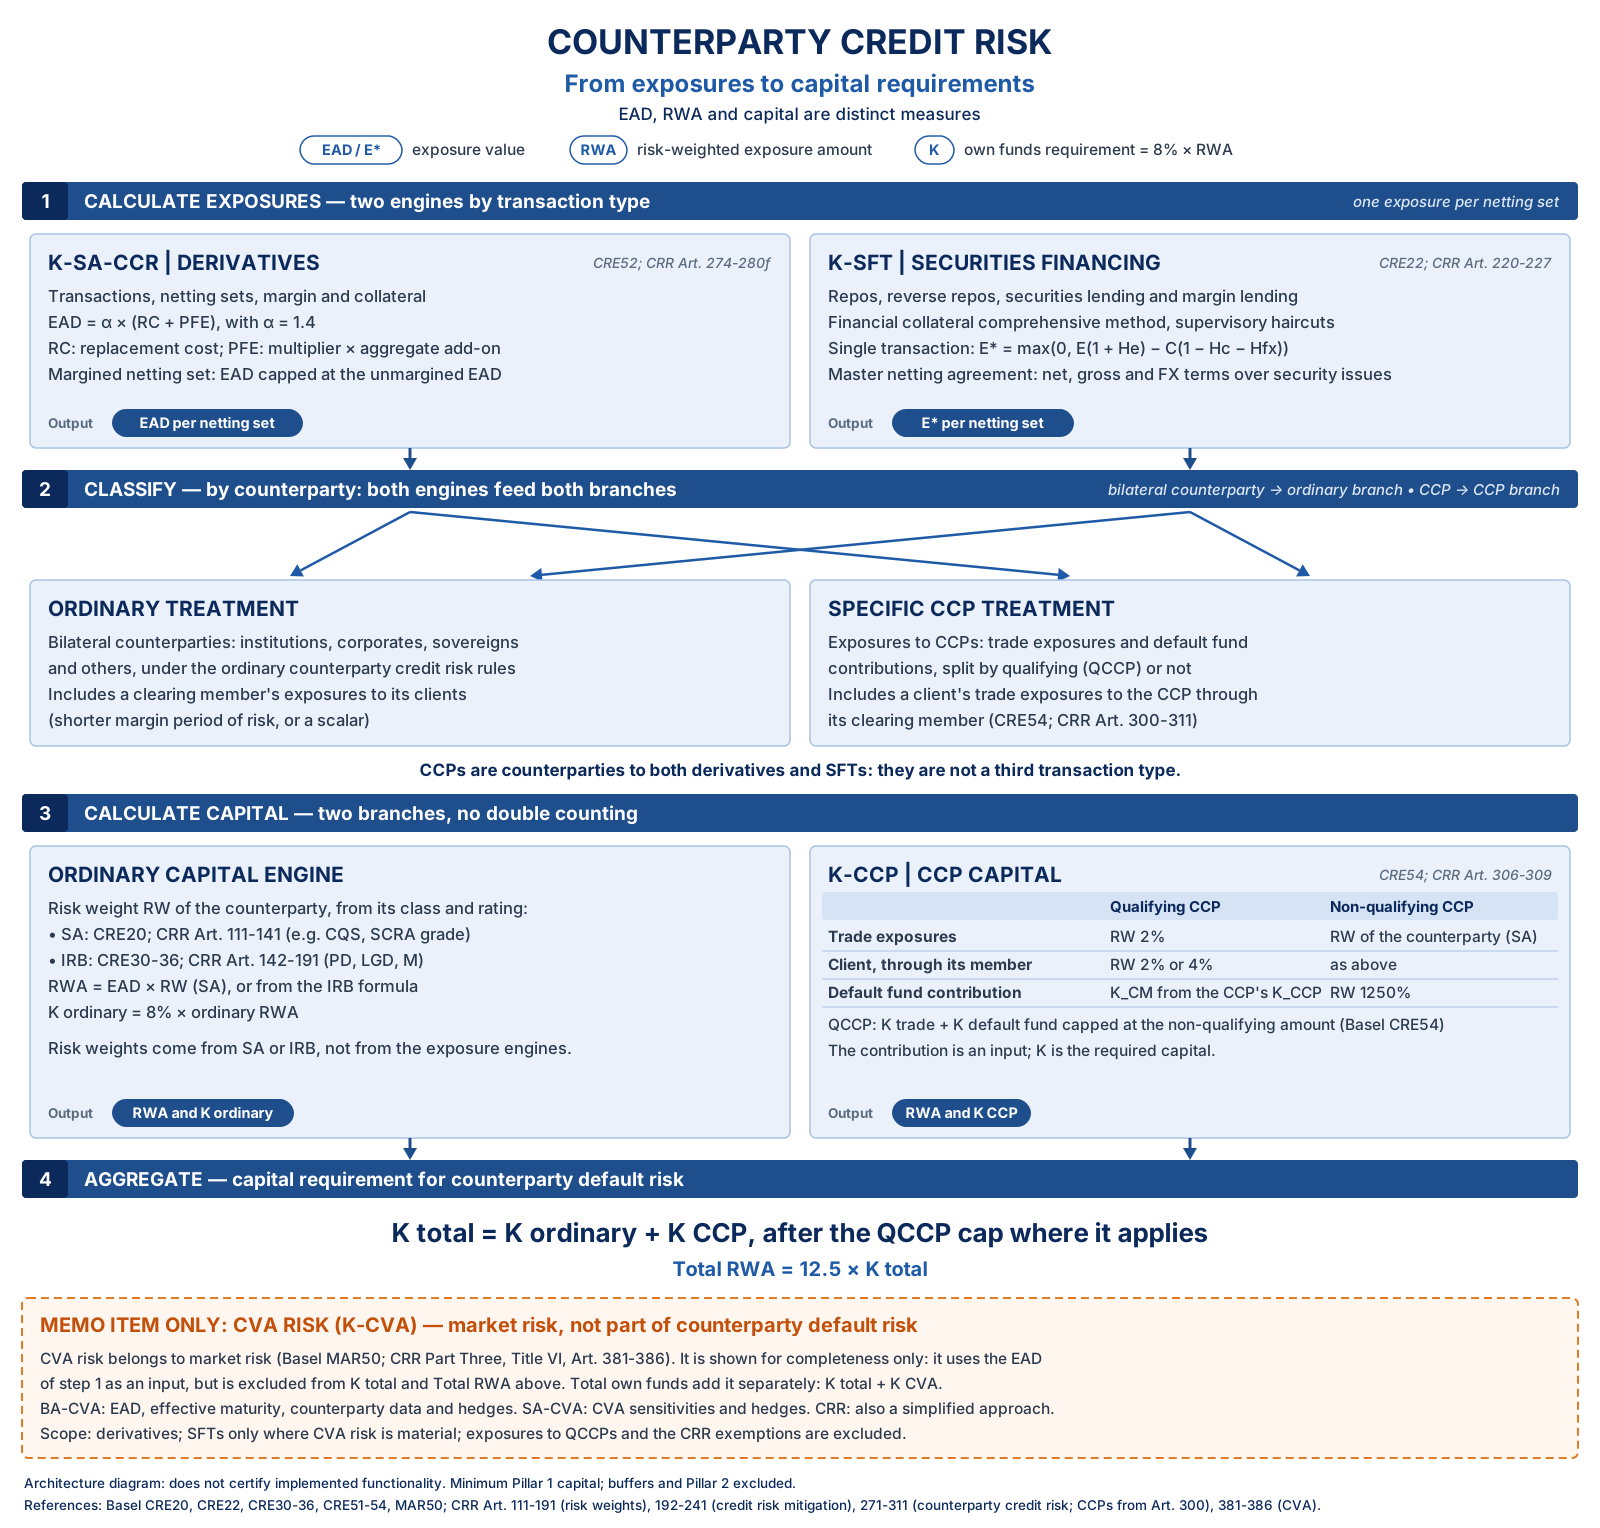
K-SACCR
Can I reproduce and explain this exposure?
Inspect SA-CCR calculations from trades to exposure at default, with EU CRR and Basel calculation regimes and a traceable calculation workflow.
Project-reported status. Version 1.0.2 is the current release: the 1.0.2 GitHub Release carries the workbook and the user manual.
Latest published release: v1.0.2.
Full status and limitations
Version 1.0.2 is the current release: the 1.0.2 GitHub Release carries the workbook and the user manual. The engine implements EU CRR and Basel CRE52, but only Basel rules are validated in v1.0.2, by the published CRE99 examples. CRR rules are implemented and tested against illustrative values, not validated (methodology).
Read the source README ↗
Last closed milestone: v1.0.2 - Clearing Coverage and CCP Completeness (2026-10-23).
IRRBB · Non-maturity depositsProject snapshot
K-IRRBB NMDs
What assumptions describe deposit behaviour?
A project for modelling customer rates, stable balances and deposit decay, with transparent assumptions and independently testable calculations.
Project-reported status. v0.2.0 – Workbook, data and Excel tests (in progress).
No published stable release.
Full status and limitations
v0.2.0 – Workbook, data and Excel tests (in progress). The v0.1.0 foundation, closed on 2026-10-09, established source layout, documentation, issue governance, CI and static source checks; v0.2.0 builds the first workbook, data import and Excel test harness. Neither delivers pricing, econometric fitting, a production workbook or certified IRRBB outputs. - Decay model (draft, not validated, milestone v0.3.0): core, public facade IRRBB_Decay, harness cases and example, reviewed on release/v0.3.0 and present here since this branch was levelled with main; built to MODEL_CONTRACTS.md and under review in #36; no Excel evidence is recorded yet. Rate and stable-amount models are not built. - Application profile: an Excel workbook will be the end-user deliverable, assembled from reviewed exported VBA source. - Production calculations live in src/core/ without direct Excel object dependencies; at present the data import's parsing, validation, summaries and fingerprint, and the draft decay calculations. - src/modules/ exposes the documented public facade (the data import and the draft decay model, listed in docs/PUBLIC_API.txt); src/workbook/ contains host glue only. - tests/ holds synthetic fixtures, expected results and the VBA regression harness; evidence from a real Excel run must be separately recorded. - No client data, confidential third-party material, vendor source code or customer-specific models are allowed in Git; the repository and its history are public.
Read the source README ↗
Last closed milestone: v0.1.0 - Repository foundation (2026-10-09).
Market riskProject snapshot
K-FRTB-SA
How do risk inputs become a capital requirement?
Inspect standardized market-risk aggregation across the sensitivities-based method, default risk charge and residual risk add-on. Sensitivities are inputs to the calculation.
Project-reported status. Version 0.1.0 is a prototype of the v0.1.0 — SA prototype milestone (issue #20).
No published stable release.
Full status and limitations
Version 0.1.0 is a prototype of the v0.1.0 — SA prototype milestone (issue #20). It implements the Basel standardized approach (MAR21-MAR23) in Excel VBA with parameters checked against the BIS text, and every output is reconciled with an independent Python reference. It has not yet been compiled or run in Excel, the engine platform decision is still open (scope), and no result is validated for regulatory use (validation).
Read the source README ↗
Last closed milestone: v0.0.1 — Repo setup (2026-10-18).
IRRBB · Loan prepaymentsProject snapshot
K-IRRBB Prepayment Models
How might early repayments change cash flows?
A new project for transparent loan-prepayment assumptions in Excel/VBA, supporting IRRBB and ALM benchmarking and independent model challenge.
Project-reported status. Current status: specifications only.
No published stable release.
Full status and limitations
Current status: specifications only. Repository setup (v0.1.0) closed on 2026-10-21 with accepted data, model and validation contracts; prototype setup (v0.2.0) is the open milestone. No prepayment model, VBA engine, workbook, calibration routine or validated numerical output is delivered. These are development objectives, not implemented features.
Read the source README ↗
Last closed milestone: v0.1.0 - Repo setup (2026-10-21).
Project snapshotK-SFTs
Securities financing transaction counterparty credit risk: a project under development.
Project-reported status. Status: repository setup only.
No published stable release.
Full status and limitations
Status: repository setup only. There is no calculation engine, public API, production workbook or validated method yet. Nothing here should be used to compute exposure. The regulatory basis is chosen: the EU CRR controls, with the Basel Framework as the methodological reference. The first scope is bilateral SFTs under the Financial Collateral Comprehensive Method; products, collateral and outputs are still open decisions.
Read the source README ↗
Last closed milestone: none recorded.
Private projectK-CVA
Part of the risk-model portfolio. The repository is currently private; public scope, implementation status and validation evidence are not available here.
Portfolio snapshots are refreshed through reviewed updates. Status quotations describe each engine: paths, issue numbers and references to “this repository” belong to the source project. Read its full status and limitations; release availability and milestone closure do not establish model validity.